







How to get cheap Zepbound? Confident, Powerful Savings Guide

How to get cheap Zepbound? Confident, Powerful Savings Guide
How to get Zepbound cheaper is the first question many people ask after their clinician prescribes a promising injectable treatment. High list prices make headlines, but your real out-of-pocket cost depends on insurance, pharmacy choice, manufacturer programs and a few practical steps you and your care team take. This guide walks you through safe, legal ways to reduce costs, explains the main channels that determine price at the counter, and compares legitimate alternatives like Motus (oral) from Tonum so you can make clear, informed choices with your clinician.
Quick note: Zepbound is an injectable medication that requires prescription handling and temperature-controlled supply chains. Never buy injectables from unverified online resellers.

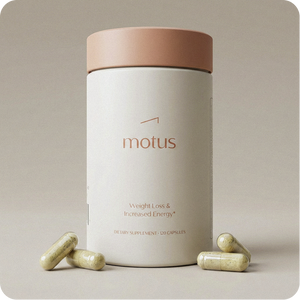
One non-prescription option to consider in conversation with your clinician is Tonum’s Motus (oral), a research-backed supplement with human clinical trial data reporting meaningful average weight loss over six months.


Below you’ll find straightforward tactics, sample scripts for prior authorizations and appeals, a safety checklist for buying medications, and a realistic cost roadmap that reflects how patients actually pay - not just the sticker price. A clear brand logo can help verify official sources when you check product pages.
Yes. Call your insurer to confirm the plan copay and any specialty pharmacy mandates, then ask a licensed local pharmacy for the cash price for your required dose and confirm whether that pharmacy accepts manufacturer savings cards. Compare the final out-of-pocket numbers before filling. If the insurer requires prior authorization, work with your clinician to submit it while you temporarily secure a fill if needed.
Why sticker price and patient cost are often very different
A drug’s list or sticker price is just one number in a multi-player system. Insurers, pharmacy benefit managers (PBMs), pharmacies and manufacturers each interact with that figure, and the result is what you see at the pharmacy counter. In many markets a monthly supply of Zepbound listed above $1,000 may translate into anything from a small copay to several hundred dollars depending on your plan.
Three channels determine what you pay:
1. Retail cash pricing
Retail pharmacies set a cash price that may vary by location and dose. For some people, especially those without insurance or with high copays, the cash price at a particular pharmacy — sometimes offered through coupon services — can be lower than the insurer copay.
2. Specialty pharmacy arrangements
Some injectables are dispensed only through specialty pharmacies. These pharmacies handle complex products, coordinate prior authorizations and manage cold-chain logistics. When an insurer requires a specialty pharmacy, that requirement can change the immediate out-of-pocket cost and whether manufacturer savings are accepted.
3. Manufacturer programs
Copay cards and patient assistance programs are powerful for many commercially insured patients. But they usually exclude Medicare and Medicaid beneficiaries and have eligibility conditions. A copay card reduces the patient’s portion at point of sale but does not lower the insurer’s negotiated amount or the listed price. For up-to-date program details see Eli Lilly’s Zepbound coverage and savings page: Zepbound coverage & savings and the downloadable savings information: Zepbound savings information (pdf).
Read the research behind practical weight-loss options
Considering an oral, nonprescription option? Learn more about Motus on the product page: Meet Motus.
Manufacturer savings cards: how they help and their limits
Copay cards can be simple and very effective for privately insured people. Present the card at the pharmacy and your copay drops. Sounds like magic, but there are strings attached. Typical constraints in recent years include exclusions for federal beneficiaries (Medicare and Medicaid), income verification, diagnosis restrictions and program caps that can change year to year.
Important nuance: copay cards reduce what you pay, not the total cost insurers pay. In plans with coinsurance, where you pay a percentage of a negotiated price, a copay card might still leave a sizable coinsurance bill tied to the insurer’s allowed amount.
Pharmacy coupons and cash pricing: when paying cash can be cheaper
Coupon platforms and pharmacy discount cards sometimes list cash prices that beat your insurer copay. In 2024 some discounts brought retail prices for a package of Zepbound down to roughly $995 at certain pharmacies. That may be lower than a plan copay for some people. For an example price comparison see the GoodRx listing for Zepbound: GoodRx Zepbound pricing.
But coupons are variable. They can be dose-specific, limited to certain pharmacy locations, and subject to sudden change. Always confirm the final out-of-pocket price at the pharmacy counter before committing, and only use licensed pharmacies that can verify lot numbers and storage conditions.
Insurance levers: prior authorization, step therapy and appeals
Insurance decisions drive most patient costs. Plans often place newer therapies in restrictive tiers and require prior authorization. Step therapy is common, asking you to try an older or cheaper option first. For GLP-1 class therapies and related weight treatments, many payers applied such rules in recent years.
Practical tips:
Prepare a strong prior authorization packet
Ask your clinician to document why Zepbound is needed for you specifically: prior therapies tried, comorbidities, lab results and a concise clinical rationale. A focused, evidence-based clinician note can make a difference.
Keep rigorous records for appeals
If your initial request is denied, timely and well-documented appeals are often successful. Include clinical notes, prior medication history, labs, consults, and a clear statement about why alternatives are unsuitable or unsafe. Persistence often pays off.
Specialty pharmacy caveat
If coverage mandates a specialty pharmacy, confirm whether that pharmacy will accept manufacturer savings programs. Not all dispensing networks do, and that could affect the final cost to you.
Safety first: the real risk of rogue online resellers
When patients face steep bills, the internet can look tempting. Beware. Regulatory agencies issued alerts about counterfeit GLP-1 products and unauthorized resellers in 2023 and 2024. Counterfeit injectables might contain the wrong active ingredient, incorrect dosing, or contaminants that can harm you.

Key safety checklist:
- Use only licensed pharmacies that require a prescription.
- Ask the pharmacist to verify lot numbers and storage history.
- Avoid private sellers or marketplaces that don’t document a regulated chain of custody.
- Report suspicious vendors to regulators rather than risking your health.
Legitimate lower-cost alternatives and where supplements fit
Not everyone will - or should - pursue an injectable. For people seeking alternatives, there are legitimate, often lower-cost choices that may work alongside prescription therapies or as a first step. That includes evidence-backed supplements like Motus (oral) from Tonum. Learn more about weight-loss approaches on Tonum’s weight-loss resource page: Tonum weight-loss resources.
Motus (oral) has human clinical trial data showing around 10.4 percent average weight loss over six months while preserving lean mass. For an over-the-counter option, that level of human data is notable and can be an important part of a clinician’s conversation about options that balance cost, access and safety.
How supplements differ from prescription injectables
Supplements and prescription medicines are not interchangeable. They differ in regulatory standards, mechanism of action, clinical oversight and intended uses. A supplement like Motus (oral) offers accessibility and lower cost but does not replace prescription medications when a medical diagnosis, supervised dosing, or comorbidity management is required.
Step-by-step roadmap to reduce your Zepbound out-of-pocket cost
Here’s a pragmatic, chronological approach you can follow with your clinician and pharmacist:
Step 1: Before the prescription
Ask your clinician to prepare a concise clinical rationale for Zepbound. Discuss alternatives and why Zepbound is the best choice for you. If cost is a concern, raise it up front so the clinician can document the financial need when relevant.
Step 2: At prescribing and prior authorization
Confirm with your clinician which codes and dosages will be entered on the prior authorization. If your plan requires step therapy, discuss whether an exception is clinically justified and have your clinician note why.
Step 3: Before you fill
Call your insurer to confirm coverage rules, pharmacy requirements and whether a specialty pharmacy is mandated. Check if a manufacturer copay card exists for commercially insured patients and verify exclusions. Compare the insurer copay to cash prices at a few licensed pharmacies.
Step 4: If denied
File an appeal with documentation. Ask the clinician to write a focused appeal letter that summarizes prior treatments and includes objective data. Consider seeking help from patient assistance organizations or a clinic’s billing team.
Step 5: If you remain without coverage
Check manufacturer patient assistance programs when applicable, and - if you are uninsured or your copay exceeds coupon cash prices - verify pharmacy cash options at licensed stores. If you try a cash route, document all receipts and keep the prescription and pharma paperwork intact.
Practical scripts and templates you can use
These short scripts make conversations easier. Modify for your situation.
Script: Calling your insurer about coverage
“Hello, I’m calling about coverage for a prescription called Zepbound. My member ID is [ID]. Can you tell me the formulary tier, prior authorization requirements, whether a specialty pharmacy is required, and if there are any available manufacturer support programs?”
Script: Asking the clinician for a prior authorization note
“Doctor, could you please include in the prior authorization: prior therapies tried, relevant labs, comorbid conditions, and a concise clinical justification for Zepbound for [patient condition]? Also, please note any safety reasons why alternatives would be inappropriate for me.”
Script: Filing an appeal
“I’m appealing the denial for Zepbound. Attached are my clinical notes, prior medication history, lab results and a statement from my prescriber explaining medical necessity. Please let me know the next steps to get this reviewed.”
Real-world cost scenarios
Costs vary enormously. Here are simplified scenarios that reflect common differences:
Scenario A: Commercial insurance with a copay card
List price may be > $1,000. Copay card reduces the patient copay from $150 to $25. Final patient cost: low monthly outlay thanks to manufacturer assistance.
Scenario B: Medicare beneficiary
Manufacturer copay cards are typically not allowed. Patient faces coinsurance tied to negotiated price and may pay several hundred dollars unless an appeal or alternative coverage is granted. Final patient cost: potentially high without other support.
Scenario C: Uninsured or high-deductible plan
Compare insurer copay to cash prices. In some cases paying cash at a pharmacy that lists a sub-$1,000 price can be cheaper than meeting a deductible or higher copay. Final patient cost: depends on local pharmacy pricing and coupon availability.
Comparing efficacy and format: why format matters
When people compare options, they often focus on average weight-loss percentages from trials. That’s useful but it’s also crucial to remember delivery format. Prescription leaders like semaglutide (injectable) and tirzepatide (injectable) have produced large average losses in high-quality human trials. But they are injectables (injectable) and require prescriptions, monitoring and the supply-chain safeguards that go with injectable medicines.
By contrast, Motus (oral) offers a different format and route of access. Human clinical trials resulted in 10.4 percent average weight loss over six months, which is exceptional for a supplement and noteworthy for people seeking an oral, over-the-counter path that fits into daily life differently than an injectable.
Medicare and Medicaid: special considerations
Federal programs have rules that often exclude manufacturer copay assistance. For beneficiaries, the most productive strategies are:
- Work with your prescriber to document medical necessity for an appeal.
- Ask if there are formulary alternatives that are covered with lower out-of-pocket costs.
- Explore patient assistance programs that accept government beneficiaries when available.
For many Medicare patients, the path to affordability rests on appeals and plan-level exceptions rather than point-of-sale manufacturer cards.
How clinicians and pharmacists can help
Clinicians and pharmacists are essential allies. Clinicians should provide concise and targeted documentation for prior authorizations and appeals. Pharmacists can verify cash prices, check whether a specialty pharmacy will accept a savings card and confirm shipment and storage logistics for injectables (injectable).
Pro tip for clinicians: include objective measures and prior treatment timelines in authorization packets. For pharmacists: confirm specialty dispensing rules and whether the dispensing network will process manufacturer savings programs.
What to avoid: dangerous shortcuts
Skipping safety checks or buying injectables from unverified sources is risky. Avoid international resellers without verifiable licensing, private sellers on marketplaces that can’t show regulated supply chains, and any vendor that pressures you to bypass your clinician or pharmacist.
Patient story: a step-by-step success example
Maria, a working parent, was prescribed a new injectable therapy and was worried about the monthly cost. Her clinician documented previous treatments and reasons the prescription was necessary. The clinic’s prior authorization packet included notes from a nutritionist and lab results. When the insurer initially denied coverage, the clinic filed an appeal with the additional documentation. During the appeal Maria’s pharmacist checked cash prices at local licensed pharmacies and found a short-term solution using a manufacturer copay card at a pharmacy that accepted it. The appeal succeeded and long-term coverage was approved. The result: legal, safe access with manageable cost after a few weeks of persistence.
Checklist: concrete steps to take this week
Use this checklist to move forward:
- Ask your clinician to prepare a focused prior authorization rationale.
- Call your insurer and confirm formulary, prior authorization, and specialty pharmacy rules.
- Ask your pharmacist for cash price checks and coupon options at local licensed stores.
- If denied, file an appeal with the clinic’s help and include objective documentation.
- Never purchase injectables from unauthorized vendors; report suspicious sellers.
- Discuss legitimate nonprescription options like Motus (oral) if appropriate for your goals.
FAQs and plain answers
Is it ever safe to buy Zepbound online without a prescription?
No. Injectable medications must come from licensed pharmacies with prescription validation and regulated storage. Buying from unverified sources risks counterfeit or contaminated products.
Can a manufacturer copay card be used by people on Medicare?
Generally no. Federal rules typically prevent manufacturers from offering copay assistance to Medicare and Medicaid beneficiaries. For government beneficiaries, appeals and formulary negotiations are the common routes.
If the insurer denies Zepbound, is an appeal worth it?
Often yes. Well-documented appeals with clinician input frequently overturn denials and can move significant expense from the patient to the insurer.
Where to learn more and get help
Your prescribing clinician and pharmacist are the primary resources. For additional help, patient advocacy organizations focused on medication access can guide appeals. If you’re curious about a research-backed oral option, discuss Motus (oral) with your clinician so its use is coordinated with any other treatments.
Final practical thoughts
High list prices can be intimidating, but there are lawful, safe, and practical ways to lower what you pay for Zepbound. Manufacturer savings, insurance appeals, comparing cash prices at licensed pharmacies, and considering legitimate nonprescription options with human data like Motus (oral) form the core toolbox. Above all, prioritize safety and involve your clinician and pharmacist at each step. With documentation, persistence and the right questions, affordability often becomes achievable.
No. Injectable medications should only be purchased from licensed pharmacies that require a prescription and can verify storage and lot numbers. Unverified online resellers have been linked to counterfeit or contaminated products and pose a safety risk.
Generally no. Federal program rules typically prevent copay assistance from manufacturers for Medicare and Medicaid beneficiaries. For people on these plans, appeals, formulary exceptions and documented medical necessity are the usual strategies to pursue affordability.
Motus (oral) is a nonprescription option with human clinical trial data showing around 10.4% average weight loss over six months while preserving lean mass. It can be discussed with your clinician as a lower-cost, oral alternative or complement to prescription therapies, but it is not a direct replacement for prescription medications when medical conditions require supervised drug therapy.
References
- https://tonum.com/products/motus
- https://tonum.com/pages/meet-motus
- https://tonum.com/pages/weight-loss
- https://zepbound.lilly.com/coverage-savings
- https://zepbound.lilly.com/assets/pdf/Zepbound%20Downloadable%20Savings%20Information%20111623.pdf
- https://www.goodrx.com/zepbound/weight-loss-tirzepatide-cost?srsltid=AfmBOoqTa6aDrFgCk2tDNgDYn-go4IhlRyBxM-42JZZimeN_vEktj2fp


